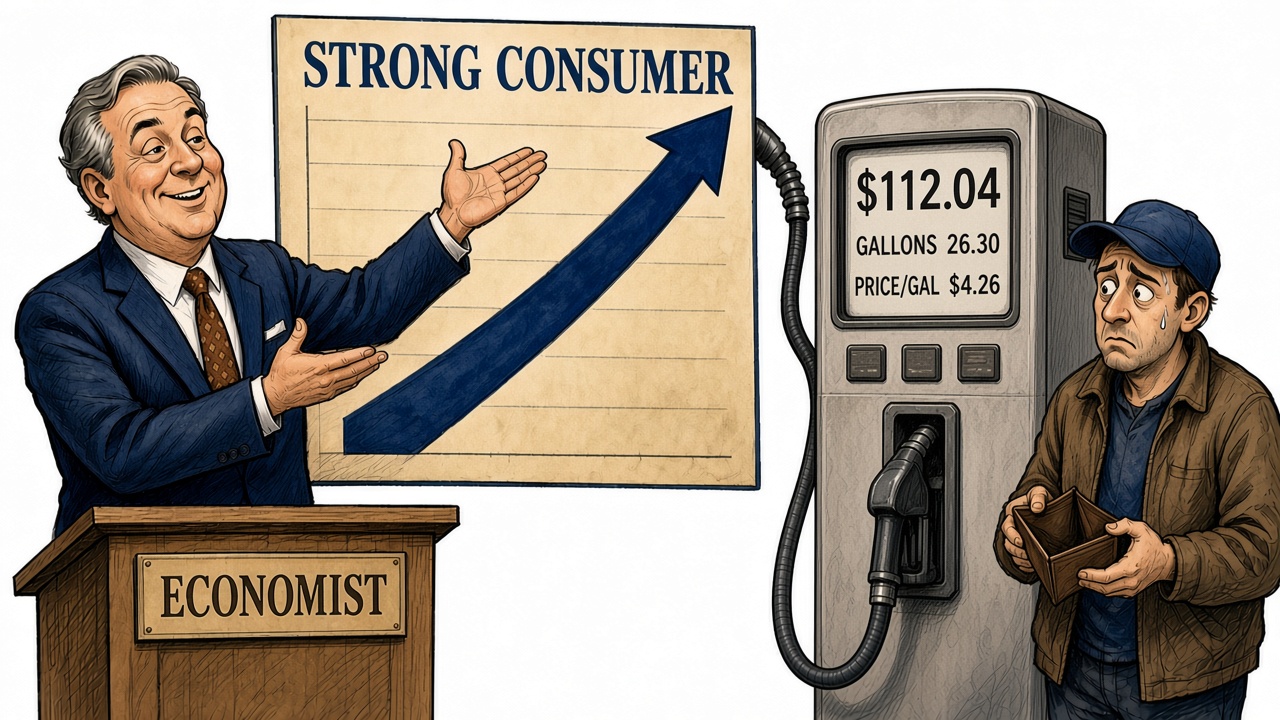
I paid over $100 yesterday to fill up the tank of a 2019 Toyota Sequoia. And I wanted to throw up. That tank holds 26.4 gallons (EPA). Regular was $4.26 a gallon yesterday, up from $3.05 a year ago (AAA). A full tank is about $112.
I wrote Pain at the Pump back in April, right after we went into Iran. The point then: we drill our own oil, but we pay the world price. Why? Oil trades on a global market, so a barrel stuck behind Hormuz raises the price of every barrel, including ours. Unfortunately, this is still true.
When retail sales jumped 0.8% in September (Census), the data didn't show a shopping spree. Gas station sales rose 6.4% (Census). The control group, the slice that feeds GDP, rose 0.1% (Reuters). Same gallon, bigger receipt.
Interactive · Tap a bar
Where did September's 0.8% go?
Change from August to September 2026. Gas did the heavy lifting.
September retail sales, month over month
Filling a 2019 Toyota Sequoia (26.4 gallons)
Sales at gas stations jumped mostly because each gallon cost more. Gasoline prices rose 9.1% in September.Source: Census Bureau; BLS CPI
Why hasn't it come down? Brent touched $112 this week as tankers kept getting hit near Hormuz (Reuters). Up to 10% of global refining is offline (Dallas Fed). And pumps fall slower than oil (ABC News). Diesel is $6.28 (EIA). That's how a gas problem becomes a grocery problem.
Meanwhile, money is pouring in to build. Investment in computing equipment has grown more than 20% a year since early 2025, faster than the late 1990s boom (San Francisco Fed). The four biggest cloud companies plan to spend over $700 billion this year (TMT Finance).
This is Econ 101. All that building pushes demand up. The war and refinery outages knock supply down. Demand runs ahead of supply, so prices rise. Over time, those data centers and plants add capacity, and the economy produces more. We are in the short run. The long run is the one I wrote about in The Bullish Case Is Being Built. That piece is the payoff. This one is the bill.
The price at the pump comes down when the shooting stops. We need to finish what we started. Until then, read the receipt and pray our leaders made the right call.
Sources
- EPA and DOE, fueleconomy.gov, 2019 Toyota Sequoia 2WD (tank 26.4 gal)
- AAA national average (10/21/26: regular $4.2644; year ago $3.0478)
- U.S. Census Bureau, Advance Monthly Sales for Retail and Food Services, September 2026, Oct 15, 2026
- Reuters via Investing.com, Lucia Mutikani on September PPI and retail sales (control group +0.1%), Oct 15, 2026
- Reuters via Euronext, "Brent slips as Iran president discusses mediation with Pakistan army chief," Oct 20, 2026
- U.S. Bureau of Labor Statistics, Consumer Price Index, September 2026, Oct 14, 2026 (all items +0.6% seasonally adjusted; gasoline +9.1%)
- Federal Reserve Bank of St. Louis, FRED, Advance Real Retail and Food Services Sales (RRSFS; Census sales deflated by CPI; Sep 2026 221,536 vs Aug 221,267, +0.1%)
- Dallas Fed, "Refinery outages pumping up fuel prices more than cost of crude oil," Oct 8, 2026
- ABC News, "Why are gas prices still high even as traffic improves in the Strait of Hormuz?" Oct 8, 2026
- EIA Gasoline and Diesel Fuel Update (diesel $6.276 on 10/19/26)
- San Francisco Fed, SF FedViews, "AI and Energy Shaping the Outlook for Growth and Inflation," Sylvain Leduc, Oct 15, 2026 (real investment in information processing equipment up more than 20% average annualized since start of 2025, above the late 1990s boom; BEA data)
- TMT Finance, "2026 hyperscaler capex tops US$700bn," Aug 18, 2026 (Alphabet, Amazon, Meta, Microsoft combined 2026 capex guidance $720bn to $745bn, from Q2 2026 earnings calls)
- TCE, Pain at the Pump (April 13, 2026)
- TCE, The Bullish Case Is Being Built (October 17, 2026)